
Need home insurance?
Use our customer scores to help you choose a great deal at MoneySuperMarket
Compare dealsWhich? earns commission to fund its not-for-profit mission if you buy a product
By clicking a retailer link you consent to third-party cookies that track your onward journey. This enables W? to receive an affiliate commission if you make a purchase, which supports our mission to be the UK's consumer champion.

Dean is an award-winning personal finance writer who’s spent over 15 years helping consumers navigate the tangled and fascinating world of insurance.

We've partnered with MoneySuperMarket to help you compare a wide range of home insurance options in one place, with added insight from Which?
Get a quote with MoneySuperMarket and we'll highlight Which? Best Buys and Recommended Providers in your results.
This is a Which? exclusive, so you won't find our scores or expert analysis on other comparison sites.
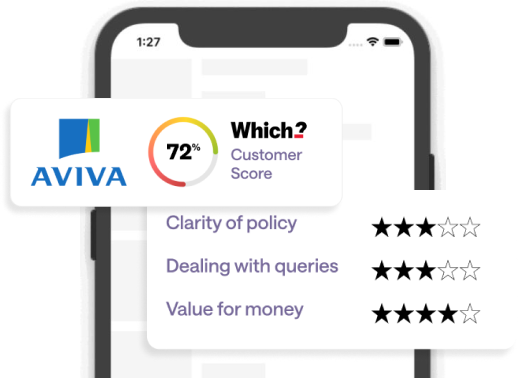
We rated 177 elements of each policy, covering buildings, contents and admin points such as fees.
We asked 3,419 home insurance customers who made a claim within the past two years to score their insurer.
Everyone's home is different, and the features your home insurance policy offers as standard may not be enough.
Insurance add-ons provide a way to get cover that matters to you without paying extra for features you don't need.
Not sure what cover you already have? Our home insurance reviews list some of the add-ons available from each insurer, as well as what's covered as standard.
Use our customer scores to help you choose a great deal at MoneySuperMarket
Compare dealsWhich? earns commission to fund its not-for-profit mission if you buy a product
The likelihood of you using a particular feature of your policy will vary depending on your specific circumstances. However, it's fair to say that some add-ons are well used when looking at the big picture.
When we surveyed people who had claimed on their home insurance, accidental damage to property and home emergencies were the first and second most common claims (out of 14 types of claim). A fifth (22%) of respondents had claimed for accidental damage in the past two years, and one in six (17%) had made a home emergency claim.
In our policy analysis, cover for both was usually an optional extra and what was included varied.
The third most common claim was damage caused by high winds, rain or hail, which should be covered under your standard policy.
Accidental damage cover usually refers to one-off incidents – general wear and tear isn't included.
Policies sometimes include limited accidental damage cover as standard. With buildings insurance, this typically includes things such as accidental breakages of window glass or damage to pipes or cables. With contents cover, this can mean damaged audio-visual equipment or furniture.
For more complete cover – for accidental damage to everything else that's covered under your buildings or contents – you'll usually need to buy an add-on.
Home emergency cover is designed to provide rapid assistance for an urgent problem such as a burst water pipe or broken boiler.
This cover, which can cost around £50 a year, can help with emergencies ranging from plumbing issues and electrical faults to problems with pests or vermin.
What policies offer, and the levels of cover, vary significantly between home insurers, so check your policy's T&Cs.
A personal possessions add-on covers portable items while you're away from home or abroad such as your handbag, mobile phone or tablet.
Just 6% of claimants in our survey had most recently made a personal possessions claim.
Restrictions apply, so check the T&Cs before you buy. Also consider the excess for claims, and whether it would be worth claiming.
This add-on covers the cost of legal proceedings if you need to take legal action or defend a claim.
Just 4% of claimants in our survey said they had last made a legal expenses claim. This typically covers the legal expenses incurred in most personal injury, consumer, property and employment disputes, as well as any award of the other party's legal costs. A few insurers include this cover as standard, but most will charge an additional fee.
For a claim to be taken up, your insurer must be satisfied that you have a reasonable or better-than-average chance of winning your case at any time, not just when the claim is first raised.
Some home insurers have clauses that limit the hourly rate they pay their panel solicitors (likely far below the industry's agreed rate). This could limit the quality of solicitors you're likely to get.
Legal expenses cover is not the same as liability cover. The latter is typically included in standard home insurance and covers you if you're liable for damages.
If you own a bicycle, it will likely be covered as standard under your contents cover when it's in your house – but in most cases, you'll need to pay extra to cover your bike when you're out using it.
Bicycle cover will typically protect you against theft and accidental damage. Cover limits can vary, however, as can the range of the cover: some policies will cover you in the UK; others also cover Europe and beyond.
Find the right policy for your home using the service provided by MoneySuperMarket
Get a quote now