
Need home insurance?
Use our customer scores to help you choose a great deal at MoneySuperMarket
Compare dealsWhich? earns commission to fund its not-for-profit mission if you buy a product
By clicking a retailer link you consent to third-party cookies that track your onward journey. This enables W? to receive an affiliate commission if you make a purchase, which supports our mission to be the UK's consumer champion.

Dean is an award-winning personal finance writer who’s spent over 15 years helping consumers navigate the tangled and fascinating world of insurance.

We've partnered with MoneySuperMarket to help you compare a wide range of home insurance options in one place, with added insight from Which?
Get a quote with MoneySuperMarket and we'll highlight Which? Best Buys and Recommended Providers in your results.
This is a Which? exclusive, so you won't find our scores or expert analysis on other comparison sites.
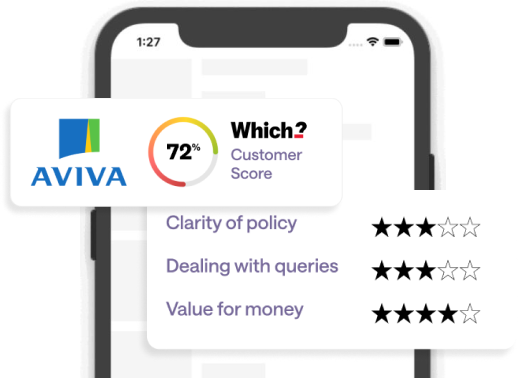
We rated 177 elements of each policy, covering buildings, contents and admin points such as fees.
We asked 3,419 home insurance customers who made a claim within the past two years to score their insurer.
How our tests find you the best
Which? fee score
Save time by checking the fee score calculated by our insurance experts — the higher, the better.
Paying monthly?
Find out which insurers charge the lowest (and highest) interest rates and how to reduce the cost of payments.
We've compared the fees charged by home insurers. Our Which? fee score shows how competitive the insurer's fees are compared to its rivals.
The higher the score, the fewer (or lower) fees that are charged. APR is the interest rate you're charged for paying monthly rather than annually.
| 89% | Nil | Nil | No fee | No fee | No fee | No fee | No fee | No contribution | |
| 89% | Nil | Nil | No fee | No fee | No fee | No fee | No fee | No contribution | |
| 89% | Nil | Nil | No fee | No fee | No fee | No fee | No fee | No contribution | |
| 89% | Nil | Nil | No fee | No fee | No fee | No fee | No fee | No contribution | |
| 89% | Nil | Nil | No fee | No fee | No fee | No fee | No fee | No contribution | |
RECOMMENDED PROVIDER | 89% | Nil | Nil | No fee | No fee | No fee | No fee | No fee | No contribution |
| 89% | Nil | Nil | No fee | No fee | No fee | No fee | No fee | No contribution | |
| 89% | Nil | Nil | No fee | No fee | No fee | No fee | No fee | No contribution | |
| 82% | Nil | Nil | No fee | No fee | £35 | No fee | No fee | No contribution | |
| 82% | Nil | Nil | No fee | No fee | £35 | No fee | No fee | No contribution | |
| 82% | Nil | Nil | No fee | No fee | £35 | No fee | No fee | No contribution | |
| 81% | Variable | £0 if adjustment made online, £16.50 if made over the phone | No fee | No fee | £24.64 | No fee | No fee | No contribution | |
| 81% | Variable | £0 if adjustment made online, £16.50 if made over the phone | No fee | No fee | £24.64 | No fee | No fee | No contribution | |
| 79% | No interest - but higher premium | Nil | No fee | No fee | No fee | No fee | No fee | No contribution | |
| 73% | Nil | Nil | No fee | £25 | £39.50 | No fee | No fee | No contribution | |
| 72% | Nil | Nil | No fee | No fee | No fee | Variable | Variable | No contribution | |
| 72% | Variable | Nil | No fee | No fee | £33.60 | No fee | No fee | No contribution | |
| 71% | Did not disclose | Nil | No fee | No fee | £25 | No fee | No fee | No contribution | |
| 70% | Variable | £0 if adjustment made online, £16.50 if made over the phone | No fee | No fee | £24.64 | No fee | No fee | No contribution | |
| 69% | 20% | £0 if adjustment made online, £25 if made over the phone | No fee | No fee | £35 | No fee | No fee | No contribution | |
| 68% | 19.9% | Nil | No fee | No fee | No fee | £20 | £12.50 | No contribution | |
| 68% | Variable | £13.44 | No fee | No fee | £33.60 | No fee | No fee | No contribution | |
| 65% | Variable | £0 if adjustment made online, £15 if made over the phone | No fee | No fee | £30 | £14 | £14 | £25 per policy | |
| 63% | 22.8% | £0-£20 | No fee | No fee | £35 | No fee | £12 | No contribution | |
RECOMMENDED PROVIDER | 63% | 23.5% | £25 | No fee | No fee | £35 | No fee | No fee | No contribution |
| 63% | 29.89% | £15 if adjustment made online, £25 if made over the phone | No fee | No fee | £25 | No fee | £15 | No contribution | |
| 61% | 19.9% | Nil | No fee | No fee | £35 | £20 | £12.50 | No contribution | |
| 59% | Variable | £9.50 | No fee | £25 | £39.50 | No fee | £5 | No contribution | |
| 57% | 23.7% | Nil | No fee | No fee | No fee | £36 | £36 | No contribution | |
| 57% | 23.7% | Nil | No fee | No fee | No fee | £36 | £25 | No contribution | |
| 54% | 19.5% | £15 | No fee | No fee | £25 | £25 | £25 | No contribution | |
| 43% | Variable | £20 | No fee | £20 | £58 | No fee | £20 | No contribution | |
| 43% | Variable | £20 | No fee | £20 | £58 | No fee | £20 | No contribution |
Table notes: We examined the fees and charges of 72 policies from 30 insurers, as well as any reimbursement that insurers offer to new customers who face cancellation fees for switching to them. We rated policies in each fee area. The Which? fee score is the total number of points the policy was awarded as a proportion of the maximum score achievable. Table correct as of September 2026. See below for how we analyse insurers' fees.
Use our customer scores to help you choose a great deal at MoneySuperMarket
Compare dealsWhich? earns commission to fund its not-for-profit mission if you buy a product
The best insurers for fees in our analysis were:
These providers, along with nine others, didn't charge any of the fees we checked in the table. The reason they didn't get 100% is because they don't contribute towards the cancellation fee you might incur if you switch to them from another insurer – which would have netted them a few more points.
While these insurers were front of the pack for fees, they weren't all equally good for overall levels of cover, so fees alone shouldn't determine which insurer you pick.
Esure and Sheilas' Wheels were at the bottom of our table with fee scores of 43%. These policies had the highest cancellation fees at £58, as well as mid-term adjustment fees of £20.
Co-operative Insurance charged the highest interest if you pay monthly, with an APR of 29.89%.
Many home insurance providers charge extra for even common changes to your home insurance policy.
Some insurance companies (typically brokers) will take a fee of up to £36 for setting up the policy or renewing it.
If you're paying in monthly instalments, you could be saddled with one of the most common and costliest extra charges: interest. In our last survey of the market, we found APRs as high as 29.89%.
Some 21 of the 72 home insurance policies we reviewed charged payment default fees if you miss a monthly payment, the highest being £36.
If, while the policy is running, you need to make some alterations (for example, if someone moves in or out of your home), you may find yourself on the hook for an 'adjustment fee'. If you need extra copies of paperwork sent to you, this can incur a duplicate document charge.
If you decide to cancel your policy ahead of renewal, most providers will charge an early cancellation fee.
An insurer can even charge a fee if you cancel within the 14-day cooling-off period when you first take out the cover, provided it reflects the cost the insurer has incurred setting up the cover.
However, some insurers offer to take the sting out of switching to them early by reimbursing some or all of your cancellation fee.
Most insurers will allow you to pay for your cover monthly if you can't afford to pay upfront. For some customers, spreading payments over the year is the only practical way of paying for the cover, but it often comes at a cost.
Just over half of policies in our survey add interest to monthly payments, with APRs in some instances verging on 30%. While home insurance APRs (and the premiums to which they're applied) aren't as high as in car insurance, we still think they're often too high, as they can be comparable to what pricier credit cards charge.
One potential way to bypass the insurer's interest rate is to pay for your insurance using a credit card with a 0% interest period of at least 12 months, then pay that off in monthly instalments over the year.

Dean Sobers, Which? home insurance expert, says:
Home insurance premiums have risen in recent years to the exasperation of many policyholders, but at least they're out in the open. Admin fees are a bit more subtle.
Adjustment fees – covering fairly trivial bureaucratic costs in amending your policy to reflect changes in your circumstances – can be as high as £25. This feels a bit excessive when other providers can cover this for under £10, or for no charge at all.
The steepest admin fees are for leaving your insurer before your policy's renewal date, with some insurers claiming nearly £60 for the brush-off. And some customers might be surprised to find that (lower) cancellation charges also apply should you change your mind about an insurer during the cooling-off period, with a handful of firms charging between £20 and £25 to recoup their expenses in setting up your policy.
Most customers won't need to pay admin fees. But just as we probably won't claim and therefore probably won't pay an excess, it's still worth checking what these contingent costs could be when comparing policies. There could be a nasty sting lurking in the small print.
The Which? fee score is our assessment of how reasonable different providers' fees and charges are.
We look at seven fees, including the interest you'd be charged if you pay in monthly instalments, administrative fees for setting up the policy, penalties for missing payments, and what you'd have to pay if you cancelled your policy before renewal.
We also look at 'switching fees', which is an amount the insurer will pay towards customers who have switched to them in the middle of a year and incurred a cancellation fee from their previous provider. The switching fee is intended to help offset this cost.
Initially, we score policies out of five in each area. The lowest fees receive the highest scores (except for switching fees, where the highest fee contributions earn the most points). The fee score shows how well the policy did across all rated fee areas. Products with higher fee scores charge generally lower fees.
Interest rate and setup/renewal fees, which are likely to have the most pronounced or widespread effect on policy costs, are weighted so as to have more of an impact in the fee score than other fees (such as duplicate document charges).
Find the right policy for your home using the service provided by MoneySuperMarket
Get a quote now